Showing posts with label Home Sales. Show all posts

Tuesday, December 14, 2021

Double Dipping should be Illegal and Broker Fees Capped at 5%

For those that don't know, Double Dipping refers to a real estate broker practice where they end up representing both the home owner selling a property, and the home buyer who is seeking to purchase the same property. Normally they only get 5% of the sale value, but double dipping on the commission gives them 10%.
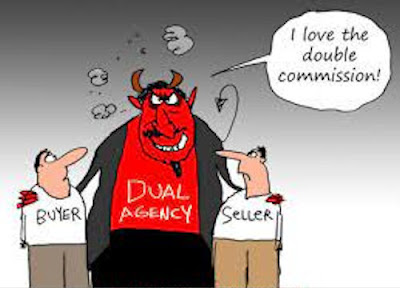
It really should be illegal.

And it is super unethical.

Why?

#1. Because it ends up favouring the home owner and unfairly raising the price of the property (and consequently contributing to housing bubbles).

#2. Because the broker ends up wanting a higher price so they can collect 10% of the total value (instead of the usual 5%), they're going to be biased towards hiding anything wrong with the property.

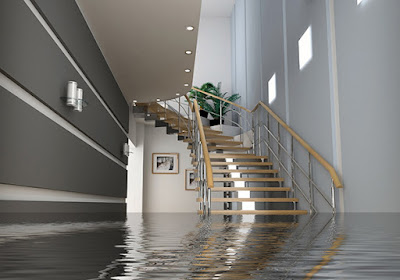
Eg. Hiding whether the property is on a flood plain, has a history of mold problems, and the roof is leaking. The double dipping broker, who wants the house to sell for more, isn't going to want to mention anything that is wrong with the house that the home buyers really should be aware of before making a purchase.

#3. Normally what you are supposed to do is have one broker representing the buyer and one broker representing the seller, and they're meant to be separate and each of them have a fiduciary duty to represent their client's interests, but when the broker represents both they are invariably biased towards the homeowner and will ignore the seller's best interests in order to get a higher sale price.

So in the example cited above, let's say someone owns a house that is on a flood plain (thanks to clay stratification), and the roof is leaking and the house has a history of mold problems... If the real estate broker is unethical and double dipping, they're not going to want to mention these three problems to any potential home buyers.

#4. Real estate brokers who are double dipping actively encourage bidding wars, knowing that if a property goes for a lot more they get 10% of that. This in turn adds to the real estate bubble, and ultimately hurts the buyer.

In Ontario double dipping is currently legal and unregulated.

If any politicians are reading this and they want to get more votes for their political party, listen well.

Make double dipping illegal and cap individual broker fees at 5%.

Then... Make it retroactive for the last 5 years and force real estate brokers who sold any houses using double dipping to issue a refund for 5% of the value of all properties they sold during that time period, giving the money back to the home buyers who got ripped off.

Politically this will lead to lots of votes for the political party who hammers this home. All the home buyers will definitely think about voting for the party that gives them an extra $50,000 or more if the house was worth $1,000,000 or more. And even if the property was $500,000, they're not going to complain about getting an extra $25,000.

That amount of money getting pumped back towards home owners will boost the economy, punish the unethical brokers, and help to soften Ontario's real estate bubble which could burst if too many things happen that hurts the market.

Who will complain?

Only the rotten real estate brokers who were doing something unethical and something that really should have been illegal in the first place. The ethical brokers won't complain. Only unethical ones will complain.

This is really something that should have been made illegal a long time ago.

Having separate brokers for the seller and buyer is a necessity, just like having separate lawyers in a divorce. Without that separation the middle man will always favour the person which is going to end up giving them more money, and that bias will lead to them hiding things.

Moral of the Story:

Buyer Beware. Double Dipping Real Estate Brokers are way worse than used car dealers. They're absolute snakes.

They make politicians look decent in comparison.
Friday, December 10, 2021

Our House is on a Floodplain. Why? Clay Stratification

Our house in North York/Toronto is on a floodplain.

I learned this recently thanks to a helpful neighbour. I was walking home from dropping off my son at school, and one of our neighbours was doing the same after dropping off his son, and we were both looking at the new construction of a building near the school.

The new building has a giant basement. Two stories. Something similar to an "iceberg home" where most of the house is actually below ground.

My neighbour was laughing at it however and predicted that it was going to get flooded...

And that was when I learned our entire neighbourhood was on a floodplain.

It wasn't something we were told about when we leased the property, but it is definitely an issue.

Now you might think, like I did: "Wait, isn't our house on a hill? How can it be on a floodplain?"

The problem is the soil.

Clay Stratification

Most drainage issues are caused by clay soil. A minor issue will be that you have standing water after a heavy rainfall for less than a day, and it will be more noticeable in your front yard and backyard. Clay soil is more dense than sandy or loamy soil, and therefore, is slower to allow rainwater to filter through it.

Clay Stratification is when you have multiple layers of dense clay, the result of millions of years of rainfall, rivers and flooding, etc. When one layer of clay stratification becomes flooded it acts like a barrier, so that water above it just sits there and can only move sideways, but not down.

Get too much water all at once, and the next thing you know your basement is flooded because it acts like a well where the water can collect. Many basements aren't designed to withstand that much water trying to get in. This is a big problem for many parts of Toronto because clay stratification is actually surprisingly common.

Why does Toronto have so much clay stratification?

Go back 12,000 years ago and all of Toronto, the GTA and the Great Lakes region was under a big inland sea. As time went by the water levels receded and it left behind layers of clay bits and loamy bits, resulting in many layers of clay and loam.

Factor in that Toronto is also effectively an ancient river delta, and yeah... That's a lot of clay.

So what can you do about it?

Knowledge is key.

#1. You need to ask "Is this property on a floodplain?"

And make a note of how the owners respond.

#2. Get it in writing.

Because people do lie about floodplains and it can lead to lawsuits when people later find out that they bought property on a flood plain. (Or bought a house with mold problems. Or bought a house with termites. The previous owners need to be disclosing these problems.)

#3. Ask "What steps have been taken to prevent flooding?"

Because chances are likely if your property is in Toronto, then it is probably on a flood plain. Even if it is on top of a hill.

#4. Get home owners insurance.

But you might also get other types of insurance too. Eg. Buyer's Title Insurance for example. Or Mortgage Insurance if you are getting a mortgage.

And flood insurance if you are in a high risk location.

Basement Flooding on the Rise thanks to Climate Change

Yeah... So this isn't a problem that is just going to go away. Places that aren't traditionally thought as being flood prone these days are getting flooded anyway. Climate Change means that Toronto now has a rainy season from April to May.

And we can still get large deluges of water thanks to freak rainstorms like that one on July 8th 2013.

I was outside when that flood happened. Toronto got 126 mm of rain in only a few hours. And while that doesn't seem like much, remember that water flows downhill and will flood basements, parking garages, subway stations, floodplains, lower streets, etc along the way.

Here's some video of what happened on July 8th 2013:


Saturday, July 30, 2016

One Unusual Way to get a House Cheap

Want to buy a house which is guaranteed to be cheaper than similar houses on the market?

Option 1: Buy the former house of a murderer.

Eg. Paul Bernardo for example. The notorious serial killer.

The house shown on the right is 57 Bayview Drive in Port Dalhousie.

It is Paul Bernardo's former house. It was purchased and torn down, with a new building being built on the lot that looks very different.

Or here is another example...

Option 2: Buy a house where the former owners were murdered by the mafia.

Barry and Honey Sherman were murdered by members of the Rizzuto crime family in their North York home. Their bodies were found near their basement swimming pool with their necks tied by belts to a railing.

The property (shown below) was later purchased for relatively cheap, the buildings torn down and the new buildings erected, but if the new owners had been fine with swimming in the pool where they had been murdered (I know it sounds creepy) they could have just let it be. Or just get rid of the pool and just have a really large rec room or garage in the basement.


Tear Down, Build Fresh?

Now you may be noticing a trend here.

The new buyers typically always end up tearing the old house down and building a brand new home.

They might keep the foundation, but if the murders happened in the basement the foundation will likely be destroyed too and a new foundation will be built.

Which means the property is ripe for people looking to renovate a building and then flip the property as an investment. Especially if a decent amount of time has passed and the property no longer looks like the previous building.

Friday, January 30, 2015

Gardening, Roof Repair + Finished Basement

Gardening

One of the ways to boost the value of your home is to plant a flower garden - especially roses, as roses are very easy to maintain and quite hardy. Rose bushes really just need to be trimmed once in awhile so they look good, and during the autumn you need to mound the dirt up around their bases to protect their roots more, so they can survive the winter easier. That is pretty much it. Some people also sometimes use powder pesticides on their roses to prevent insects from eating them, but it is not a huge necessity.

The other benefits of roses is that you have a constant supply of flowers to decorate your home with... which means prospective buyers coming to your home may see a vase of roses on the kitchen table, immediately bolstering their opinion of the place subconsciously.


 And because Valentines is almost two weeks away I thought I should include some tips about roses / vases...

Tips to Keep Your Roses Fresh in the Vase Longer

Many people love to give roses and get roses but after a couple of day the roses start to droop or dry out.  Shortly after that they wither and die and you have to throw them away.  It is such a waste and a sad way for you roses to go.  You try everything you can but you just cannot keep your roses as fresh as possible for as long as possible.  There are some old wives tales that say use sugar in the vase water, clip the ends every couple of days but do these tips really work?  Below are a few tips that may help you keep the roses from your lover a little while longer. (Or prepare a vase for prospective buyers viewing your house.)

#1. Sugar in the vase water really does help.

Sugar can help to keep your roses longer after all.  The theory is that sugar simulates the photosynthesis process and makes the flower rejuvenated.  You can use regular sugar (for a regular sized vase use about 1 teaspoon).  Or you can use leftover soda pop to produce the same effect.  Use the clear soda (Sprite or 7 Up) if you have a clear vase.

#2. Hairspray?

Yes, this works. The hairspray locks the moisture in.  All you have to do is get your hairspray bottle from your bathroom, grab your bouquet of flowers, hold the hairspray about a few inches away from the flowers and spray them well (make sure you get every section of the flower, but do not saturate them). Don't worry about the stems in the water.

#3. A Little Bit of Vodka Never Hurt Anyone

This works similarly to the sugar.  The vodka is meant to prohibit the growth of bacteria which could prematurely weaken the roses.  It may be a good idea to use in conjunction with sugar as sugar can cause bacteria to grow.  You only need a few drops so do not worry there will be plenty left for you to drink later. In theory anti-bacterial mouth wash would also work.

#4. Roofing Tar?

Wait, what? Roofing tar???

This sounds just as crazy as the hairspray idea, but if you want to keep your roses forever, this may be a great choice for you.  The roofing tar coats the entire rose and preserves it forever. A million years from now it will be a fossilized rose.

What happened was local Torontonian Rob Campbell decided to do an experiment when he decided to make black roses by dipping red roses in ToughRoof flat roofing tar. Basically all you would have to do is head to your local roofing guy who deals in flat roofing tar and ask him if he can dip your roses into the leftover roofing tar.  Within 3 minutes you should have a fresh set of a dozen roses that will never parish.  What a great way to celebrate Valentines with your loved one. (Especially if they are a goth and love black roses...)

See also
Valentines Day Black Roses made from roofing tar
How to make Black Roses using Roofing Tar

I am not sure if this would help sell your house, but hey you never know.

Roof Repair

To continue on the vein of the repairing the roof, this is another excellent way of boosting the value of your home. Having a new roof installed (after ripping out the old one), repairing the old roof by adding either new shingles or aluminum can dramatically change the look of your home and give it a fresh look - effectively a face lift for your house.

Check the before and after photos below showing what a great difference having your roof repaired makes on the appearance. To say nothing of better insulation and preventing leaks.

Or in the case of the photo at the top here, getting rid of a serious mold infestation by simply cleaning the roof.


Below - New roof plus solar panels.


Below - A lot less drab looking on the new roof.


The big thing these days is to install roofs that are plastic or aluminum and shaped like tiles or shingles.


Finished Basement

The last thing I want to discuss is the concept of making a finished basement. Not just to prevent flooding by having some basement waterproofing done (see the City of Toronto.ca page about how to prevent basement flooding or visit a website like Royal Basement Waterproofing), but also because when trying to sell your home whether you have a finished basement can be a big selling point. See the before and after photos below to see what I mean.


Having a finished basement means you can have a living room or recreational room down there. Some people even make their own private bar, or put in a swimming pool, lots of options. Like the basement swimming pool below.


At which point you have to say, who wouldn't want a swimming pool in their basement?

Saturday, February 15, 2014

American Vs Canadian Home Sale Prices

American Vs Canadian Home Sale Prices - 2000 to 2011

American Vs Canadian Home Sale Prices - 1999 to 2013.

American Vs Canadian Home Sale Prices - 1970 to 2010.

Tuesday, February 11, 2014

Toronto home prices are a big risk says BMO

Toronto home prices are a deep concern to Canadian banks - and they're banking on a drop in real estate prices.

So much so that surge in Toronto prices is described as a major economic threat in a new Bank of Montreal report.

In an economic forecast for North America released this week, BMO noted three "risks" to the North American economy, namely:

1. embattled emerging markets.
2. the continuing tussle over the U.S. government debt ceiling.
3. residential real estate in Canada’s biggest city.

Seriously, Toronto's housing prices / real estate bubble has bankers quaking in fear and using words like "collapse", "crumbling", "major economic threat", etc.

For months some economists have been trying to downplay the worries of big Canadian banks - who stand to lose a lot of money if the Toronto real estate bubble bursts. Some have tried to describe the impending doom as "a minor setback", hoping that when it happens it will simply be a market correction that causes prices to drop a mere 10% - whereas the Toronto real estate market's bubble is overpriced by about 40 to 50%. A realistic market correction would be ballparked at between 25% to 45% drop in real estate prices - and a huge unemployment rate that would send construction workers, auto manufacturers and bankers running for the hills and wanting to hibernate in a cave (bear market pun) until the chaos is over.

I find it really funny when market analysts try to downplay the size of Toronto's real estate bubble. Let me explain by doing a little economics lesson.

What is Toronto's two biggest industries?

#1. Banking.

#2. Construction.

We don't really manufacture anything, Toronto's economy is basically just banking, construction and the service/sales industry. Money pours into Toronto from Canada and the USA thanks to Canada's big banks - and a lot of that money - the lion's share - is from mortgages.

If housing prices drop, Canada's big banks lose money. If housing prices drop significantly, the banks lose a LOT of money.

Simultaneously if housing prices drop, the construction industry dries up. Construction workers are laid off, they and their families stop spending money, and thus the economic down spiral begins. A local recession ensues and many jobs are lost as companies "tighten their belts" by shedding jobs of anyone they don't see as necessary.

If Toronto has a robust manufacturing sector that ships internationally, this wouldn't be as much of a problem. South Western Ontario has a lot of manufacturing jobs, but that is over near Hamilton, Guelph, Kitchener. The auto manufacturing sector will be hit the hardest - but other types of manufacturing will be fine for the most part.

The problem however is that home prices in Toronto have skyrocketed at a ridiculous rate during the last 20 years - largely due to foreign investors in Toronto's condo market. That means that when prices start going down it won't be any minor dip. It will be more like a landslide as investors suddenly sell off their assets and flee the market in droves.

"In Canada, accelerating home prices in Toronto (7.1 per cent year-over-year in January) risk straining affordability further, causing a correction when interest rates normalize and the market is trying to absorb a record number of newly built condos," says BMO senior economist Sal Guatieri.

Mr. Guatieri’s comments follow last week’s report from the Toronto Real Estate Board, which showed the average selling price in January surged more than 9 per cent to $526,528 from a year earlier. The so-called benchmark price rose 7.1 per cent, as the BMO economist noted while warning that real estate price growth is outpacing family income by a huge margin.

In layman's terms that means Toronto home prices have become so ridiculous people can barely afford them - so a single large economic hiccup could be the flea that breaks the camel's back. The real estate market in Toronto is the keystone that holds Toronto's economy in place - give it a big bump and the whole structure collapses.

In Toronto, this is one of the bigger risks, more so to the local economy, Guatieri says in an interview. Guatieri worries what will spark trouble over the next few years is when interest rates rise.

The higher interest rates would cause people to slow their home buying - which is already slowing - and result in people looking to sell to drop their prices in an effort to find buyers. If they see a collapse coming they will be rushed to market and try to sell faster rather than later when prices will be even less.

Consider, too, that according to the latest report from the Canada Housing and Mortgage Corp., also released this week, which showed Toronto ignoring the national trend when it comes to residential construction starts.

While those across the country edged down, housing starts in the Toronto area climbed to an annual pace of 36,186 units in January from 32,281 in December - mostly bought on credit from the banks.

The six-month moving average puts the number at 36,367, up from December’s 35,547.

"Apartment starts remained high as the relatively high number of projects which began selling in 2011 reached sales targets that allow construction to begin," CMHC said of the Toronto market.

Across Canada, housing starts slipped to an annual pace of 180,248 in January from 187,144, the agency said, with the six-month moving average declining to 191,456 from 194,518.

Which means the Canadian economy is cooling, but Toronto is steaming ahead fueled by easy credit.

"The decline in starts is an indication of housing supply falling into alignment with demand in most major markets (Vancouver, Calgary, Edmonton, Quebec City)," says economist Connor McDonald of Toronto-Dominion Bank.

"However, we expect Toronto to follow suit as homes under construction reach completion and more supply comes online. Over all, the recent cooling of housing starts supports our view for a soft landing of the Canadian housing market in 2014 and 2015."

See his choice of words? "Soft landing" is his wishful thinking. He is just thinking in terms of supply and demand, he isn't thinking of what will happen when those same construction workers are laid off and the economy sours - and housing prices drop at a sharper rate than he is expecting.

In his report Guatieri notes how the boom in Canadian housing is largely over as potential home buyers adjust to tighter mortgage insurance rules brought in by the government to head off Toronto's real estate bubble - a tactic designed to prevent it from bursting.

"Not so in Toronto, however, as its prices continue to outrun median family incomes, which averaged slightly over 2-per-cent growth from 2001 to 2011," says the BMO economist.

"Consequently, affordability continues to deteriorate even with relatively steady and low interest rates. While Vancouver remains the least affordable city in Canada, some softening in prices there has allowed Toronto to rapidly narrow the gap."


Yada yada yada, Toronto can't afford these ridiculous high prices in homes so the bubble is going to burst when too much supply outpaces demand and the construction workers are all laid off.

Friday, February 07, 2014

Now is a great time to sell your home in Toronto and Vancouver

If you are thinking about selling your home in Toronto or Vancouver, 2014 is the perfect time to sell.

Act now because pundits and banks are all predicting prices to start dropping in 2015.

The real estate boards of Toronto and Vancouver are reporting year-over-year price increases of between two and twelve per cent for January 2014.

In Toronto, the average selling price for a home in January was $526,528 – up by more than 9% from a year earlier.

January property prices
Property type Toronto Vancouver Change 2013-2014
Toronto / Vancouver
All residential $526,528 $606,800 9.2% 3.2%
Detached $686,688 $929,700 12% 3.2%
Apartment/Condo $346,369 $371,500 8.7% 3.7%
Semi-detached* $481,970 $457,700* 6.6% 1.7%*
Townhouse $346,369 $457,700* 9.0% 1.7%*
Source: Toronto Real Estate Board, Real Estate Board of Greater Vancouver

*Vancouver does not separate townhouses and semi-detached homes and uses the designation 'attached properties.'
In Vancouver, the benchmark price for all residential properties rose 3.2 per cent since January 2013 to $606,800. Detached homes in Vancouver were selling for $929,700 on average last month, a 3.2 per cent increase over the previous year. Apartment and condo properties averaged $371,500, a 3.7 per cent increase over January 2013.

Sales of residential properties in Greater Vancouver were up by over 30% over January 2013 although not as strong as in December 2013, which saw sales rise 7.2 per cent above the 10-year average for the month.

There were 5,345 new listings for Vancouver on the MLS listing service last month, a 4.2 per cent increase over the same time last year - suggesting that homeowners who are looking to sell have realized now is the right time to cash in.

Toronto's market saw fewer new listings in January than last year, with 8,822 properties in the Greater Toronto Area listed on MLS, down 16.6 per cent. Sales were down 2.2 per cent over January 2013, but prices are still rising regardless of the lower volume of sales in all categories.

Detached homes in Toronto were selling for 12 per cent more than in January 2013 while the sale prices of condominium apartments were up 9.7 per cent and semi-detached homes saw a 6.6 per cent increase.

CONCLUSIONS

If you want to sell, now is a great time.

If you are looking to buy, you would be better off waiting until 2016 when the bubble has already burst and prices have dropped back down to more reasonable levels.

Tuesday, February 04, 2014

Toronto house prices to slip in 2015

TD Bank report estimates Toronto and Vancouver real estate markets are 10 to 15 per cent overvalued, compared to 10 per cent for rest of country, and due for a market correction.

The first of the big Canadian banks has weighed in with a warning that Toronto’s housing market is overvalued by 10 to 15 per cent.

So is Vancouver’s, says TD Economics in a report released yesterday, noting that both cities have been seeing “frothier conditions” than the rest of the country, where house prices remain at least 10 per cent overvalued, largely because of low interest rates which have been allowing rampant bidding wars.

“Toronto and Vancouver make up 40 per cent of the Canadian housing market, so that’s what’s really driving the overvaluation measure,” said TD economist Diana Petramala in an interview.

The coming increase in interest rates will cause a "negative economic shock" could will send resale home prices tumbling by 25 per cent, Petramala notes. But it’s far more likely there will be a “gradual unwinding of excesses” in the Canadian market as interest rates slowly rise, along with incomes, over the next few years.

Toronto home prices jumped 6.8 per cent in 2012 and 5.4 per cent in 2013, they are expected to rise just 2.7 per cent this year and then slip by 1.2 per cent in 2015, when interest rates are expected to start climbing, the report forecasts.

Thursday, January 16, 2014

Canadian real estate bubble grows 10%

The Canadian real estate bubble continues to grow as the average price of a Canadian home increased 10.4% to $389,119 (a new record high) in December 2013, compared to the same month in 2012.

The Canadian Real Estate Association (CREA) released data Wednesday showing that a total of 457,893 homes changed hands in Canada last year, an increase of about 0.8% from 2012's sales levels.

"Absent further mortgage rule changes, sales in 2014 may surpass the annual total for 2013 if demand holds steady near current levels as strengthening economic and better job growth offset the impact of further expected marginal mortgage interest rate increases," says CREA's chief economist Gregory Klump.

As has been the case for years now, CREA says the large jump in Canadian real estate prices was largely due to what was happening in Canada's most active and expensive markets - namely Vancouver and Toronto.

Canadian Real Estate Bubble to Burst?

Sales activity in December 2012 in Toronto and Vancouver was abnormally low, which dropped the national average during that time period, a sign that the growing bubble is ready to burst.

"Removing Greater Vancouver and Greater Toronto from national average price calculations cuts the year-over-year increase to 4.6 per cent," CREA said.

CREA says the average price can be misleading, as it can be too easily influenced by individual factors which drive prices up - factors like too much credit, high demand, etc.

The realtor group says its MLS Home Price Index "provides a better gauge of price trends because it is not affected by changes in the mix of sales activity the way that average price is."

That index shows home prices rose 4.31% over the past 12 months. Gains were seen in all housing types - including condos which is expected to cool sharply in 2014 - 2015.

The index was led by an 8.7% gain in Calgary and a 6.3 per cent gain in Toronto.

Vancouver's market index posted a second straight increase of 2.13% after declines for much of the time between late 2012 and late 2013.

The thing is, the higher those percentages go the bigger the bubble is then the bigger the problems will be when the prices crash.

Worried Bankers and Economists

Economists and policy-makers have been scrutinizing the Canadian housing market for indications of weakness and warning signs of a possible crash - something that is expected to happen sometime in the next two years.

"If you run a bank, you should be worried about it," says Ed Clark, the outspoken CEO of the Toronto-Dominion Bank.

Wednesday, September 25, 2013

Finding a good real estate agent

Whether you plan to sell your current home or buy a new home, you need to find a real estate agent you can depend on. Sometimes it is difficult to know where to begin looking, especially if you don't have a good and solid referral from a friend or family member.

Doing the research yourself can be time-consuming, difficult and frustrating since you won't always be able to find all the necessary information to give you a full picture of prospective agents to help you figure out who might best serve your needs. When it comes to finding the ideal realtor for you, Agent Harvest has tools and resources to make quick work of finding a real estate agent who will quickly and efficiently help you buy a new home or sell your current home.

This online referral firm specializes in finding top-rated real estate agents, leasing agents and giving you a general idea of all the things you should know about buying and selling a home. Even if you have experience with either, if you haven't been in the market either way for a while, you probably imagine things have changed. Enlisting the help of a qualified and professional agent with a high referral from a reputed agency will ease your mind since your agent will do all the leg work and heavy lifting in the purchase or sale of your home.

Looking for an agent through this performance-based referral service makes your search simpler and more clear cut since real estate agents have to meet Agent Harvest's high standards in the industry. Each agent must have a proven record of success, a detailed and intimate knowledge of your real estate market area, expertise in marketing and pricing homes appropriately and excellent communication skills. It is critical that your real estate agent returns your phone calls or emails in a timely manner, and you should know their statistics on issue this before making any other arrangements. Real estate agents will be working full-time on your behalf, following leads and generating interest in your property, so they should be committed to your success.

The referral agency will look for the top 10 rated real estate agents in your area from which you can choose. Otherwise, the agent must rank nationally or regionally or have received certification or an award of excellence to make the list of qualified real estate agents.

Tuesday, February 19, 2013

Could Software predict the Rise and Fall of Real Estate?

For decades economists have been trying to predict the rise and fall of stock market prices - and some have even postulated that it would be possible to create computer models using software which would predict how stock market prices would go up or down over both the short and long term.

But the problem with making such predictions is that there are too many factors and you can't predict accurately where things are going to go. Especially with the stock market, which is notoriously volatile.

Even with real estate it is difficult to make predictions for the future unless there is a large factor that is guaranteed to happen.

Many people turn to experienced economists to try and get predictions. But even they can be wrong when it comes to their doomsday predictions or predictions of sunny skies and smooth sailing. Its like trying to predict the weather - even the expert meteorologists suck at predicting when it will rain.

For example in 2011 economist David Madani sent shock waves through the Toronto real estate industry when he predicted that Toronto’s overheated housing market was due for a 25% correction which would result in much lower prices.

Two years later, prices have continued going up to the current point where prices have now stagnated.

David Madani is still waiting expectantly for Toronto's housing boom to falter.

Meanwhile myself, I must admit I am doing the same thing. In 2012 I predicted Toronto's condo market would collapse approx. 40% by 2015-2016 due to the over-abundance of condos that will come on the market around that time. I will be waiting expectantly to start seeing some downward movement in condo prices in Spring 2015... But that is 2 years and a couple months away, so I've got plenty of time to wait.

David Madani says he remains convinced that the most prolonged housing boom in history, fuelled largely by low interest rates, is headed for a hard landing, particularly in Toronto’s “overbuilt” condo sector. So he is looking at the same big factor I am looking at... But why was he predicting that back in 2011 and when did he think it would happen?

Well he thinks things will start to change this year - Spring 2013.

“What’s critical is what happens in the Spring,” says Madani. “If we continue to see increases in active listings as sales continue to decline, then we’ll start to see more obvious signs of prices dropping.”
The March-to-May period is traditionally the peak buying and selling season and a barometer of consumer confidence when it comes to real estate. But he is banking his prediction on a mighty big "if" that something will happen in 2013 when many more solid-minded economists are saying nothing major will happen with the prices until 2014 at the earliest.

It is true that many veteran real estate watchers can’t agree where the market is headed. There is simply too many factors to consider - and chief among them is consumer confidence, which is an often unknown factor that you cannot predict which way it will go until the time actually comes and then we see changes.

Which begs the question - could we design a piece of computer software to make predictions for us instead? If we feed enough - ENOUGH - data into the computer concerning prices, interest rates, sales rates, mitigating factors etc. shouldn't it be able to predict what the sales and prices in the near future will be?

It wouldn't be able to predict long term changes, but it might be able to predict small term changes based on current trends in the market - and using historical data we could check the accuracy of predictions.

The average sales price of a GTA home was up 4.1% in January 2013 over a year earlier, up to $482,648.

However we should note that it has actually dropped from the benchmark price by almost 1.5% just in the last six months, according CREA figures.

It really is the issue of bidding wars - a blood sport for those who can't really afford it - and some Torontonians are bidding way too much and banking on the economy to stay good and housing prices to continue going up. Sellers in Toronto have become so used to having bidding wars that they are now holding out for high prices - while buyers are realizing that they are better off waiting for deals.

So the question is, who will blink first? Will buyers give in and buy anyway? Or will sellers give in and finally lower their prices?
“Buyers and sellers remain in a standoff,” says John Andrew, Queen’s University business professor and real estate expert. “Sellers are holding out for their prices and buyers are waiting for deals. I think it’s too early yet, but there will be a correction.”
Thus predictions of slowdowns and dropping in prices has buyers interested - and sellers worried.

If someone were to make real estate software which could accurately predict when a slowdown in sales will happen - and when prices will drop - and how much prices will drop, well then that would make many real estate agents, buyers, sellers and economists sit up and pay attention.

But no such software exists.

Indeed, when you talk about real estate sofware usually people think of property management software - or online real estate databases (MLS)... things like that.

Even if someone - eg. an university professor with some serious computer skills - were to create a computer model that predicts future real estate prices then other real estate experts would step forward to naysay and claim the software is bugged and faulty, trying to point out inaccuracies in the software's predictions.

And they would be right to do so. We use such software to predict weather patterns, and it still fails despite people trying for decades to get it to accurately predict the weather.

But we have reached a point wherein the computer model is "reasonably accurate". Its off a little, but its pretty darn close to the target.

So I have to wonder, if we can do that for the weather and its reasonably accurate, maybe it is time we try and do that for predicting real estate prices?

Sunday, December 30, 2012

Vancouver Real Estate to collapse in 2013

Now when I say collapse what I really mean is a gradual decline of prices over 2013 and 2014 of roughly 25%.

Home and condo prices / sale records in Vancouver have taken a dive in 2012. Prices for single-family homes, condos and townhouses are down 4.5% and sales are down approx. 25%.

Normally the Vancouver housing market sells 88,000 homes per year. That is the average sold from the 2002 to 2011. The average typically doesn't fluctuate more than 5 to 10% above or below.

In 2012 sales dropped to 64,000 as of December 28th 2012. With only a couple days to go before the end of 2012 we really don't expect Vancouver's home sales to get above 68,000.

Especially when buyers aren't that interested in buying right now, due to combination of new mortgage changes, interests rates and the fact that almost everyone in the Vancouver real estate industry is predicting a collapse in 2013.

So here is the thing... Lets do some math. Lets say they did manage to sell 66,000 before the end of 2012. That means Vancouver's home sales are down by 25%. That is a huge drop!

To be fair the Vancouver real estate market, especially the condo market, has been in a slump since 2009. They've been kind of waiting around, half expecting a crash, but nothing really happening that would become the tipping point.

Something like a recession, to push the real estate market over the cliff. Instead its just been stagnated and in 2012 its even been in a slow decline as buyers have stopped buying.

To have a huge rapid decline, like a drop of 25 to 50% in the space of a year or two, you would need something bad to happen that would hurt the local economy. A fiscal cliff.

But it just isn't happening, which is why I am currently predicting Vancouver will continue to see a gradual decline well into 2014. I don't think we will see a huge decline in the Spring of 2013. I think we might see a sharper decline in the Autumn of 2013...

But I think Vancouver's home prices will overall drop about 20 to 25% by the beginning of 2015, and I think it will then suddenly drop an extra 15% in 2015 as Canada is hit by a recession.

Now you might say this is a pretty radical and detailed prediction for the future of real estate in Vancouver. And you are certainly free to think and say it.

But my predictions are based on pattern observation. I see a pattern developing in Vancouver, and I think that pattern shows a gradual decline until a recession in 2015.

To confirm, here is my precise predictions:

Spring 2013 - Sales slump. Normally Spring is the best time of year for real estate sales, but in 2013 it will be down on sheer volume and prices will drop about 3 to 6% compared to an all time high.

Autumn 2013 - Sales worsen. Inventory of unsold homes becomes worse. Prices drop an additional 4 to 7% by the end of the year, making the total for the year down 7 to 13%.

Spring 2014 - Pre Recession Slump. People keep expecting prices to level out and reach bottom, but prices continue to drop another 4 to 8%.

Autumn 2014 - Sales slow to a crawl. Starts to bottom out when prices hit approx. 24 to 29% below the May 2012 average price.

2015 - The recession hits Canada full throttle and prices plummet an extra 10 to 15% in 2015.

Now you might think this seems a bit extreme. But I should tell you that Vancouver's index price for single-family homes, condos and townhouses stood at $596,900 in November of 2012 – a drop of 4.5 per cent since hitting $625,100 in May of 2012 (the highest point).

All it needs to is for the average price for that index to drop another 4% to $575,000 by May of 2013. Or worse, to an average of $556,000.

And by the following year, May 2014 to drop to somewhere between $531,000 and $469,000.

I predict Vancouver's condo market will be the most effected and see the deepest slide in prices during the next 3 years. New condo builds will crawl to a stop by 2014.

How accurate my estimates are a matter of debate, but it will be interesting to wait and see if I am right.

Additional note, I am expecting one of two things in 2016.

Either prices will stay slumped, with only marginal 1% gains in 2017... Or a swift rebound of 4 to 8% in prices. But that will depend on how deep the recession is during 2015 - 2016.

I am expecting a similar slide in Toronto, but I don't expect it to dramatically effect prices in Toronto until 2014, and I am predicting the price changes in Toronto to be much more delayed and sudden. Gradual decline in Vancouver, sudden impact in Toronto.

Various other markets across Canada will also see varying degrees of gradual decline and sudden impact. I am predicting more gradual declines in Western Canada and these changes will spread eastward. When it reaches Toronto and Montreal the effect will be like an iceberg hitting the Titanic.

2015 is also when a huge surplus of condos will go on the market in Toronto due to new buildings that will be finished by that year. The surplus will be dumped on the market in 2015 and people expecting a crash in 2014 will have decided to wait a year, causing prices in 2014 to slump. When the Toronto condo market bursts in 2015 it will be sudden and dramatic, but not unexpected.

I predict condo prices in Toronto to drop 40% during the 2015 and 2016 time period and house prices to drop 20%. There will be a marginal (1 to 2%) rebound of prices by 2017.

Thursday, May 24, 2012

Moving into a New Home: 12 Hot Tips

The following is a list of 12 useful tips for when moving into a new home.

#1. Bribe your friends and family (and heck even co-workers if you have nothing to hide) with a BBQ, pizza, beer, etc.

#2. If you don't have any friends or family or co-workers you can trust then hire a professional moving company. Try to get a company that is local and trustworthy. ie. If you live in Montreal and looking for a "déménageur Montréal" then I recommend adtmoving.com just because I really like their video (shown below).


That video alone proves to me that Déménagement Montréal is a solid company. Yes, I may not speak the best French, but the video really impressed me.

#3. When carrying everything in put them all in the center of the rooms so you can paint the walls if you want to without having to move everything two extra times.

#4. If you're moving into the new home and planning to flip it later don't paint the walls willy nilly. Choose colours that everyone will like and will match your decor. This way when you later flip the house for a profit the new owners will like the paint colours and that may earn you some extra cash during the flipping process.

#5. Label all your boxes with what is in the boxes. Give each box a colour and a number. The colour is so you know which room it is going in and the number is so you can find that specific box later. The colours also help the moving men know which room everything goes in.

#6. Create a master list of the box numbers, colours and any important contents (ie. toilet paper).

#7. When in doubt move all the breakable things yourself if you don't trust anyone else to carry them. That way if you break them its YOUR fault.

#8. Always let larger / stronger people carry the big things like your grand piano. Why break your back when you don't need to?

#9. Always have a map and directions of how to get to BOTH places, your old place and the new one, and give copies to everyone. This will save time later and remove any confusion. The last thing you want is people getting lost on the way to the new place. The same rule applies for your cell phone number.

#10. Have a box of commonly used tools handy. Screwdrivers, etc in case anything needs to be disassembled before it can be carried down the stairs.

#11. If you do go the BBQ / pizza route with family and friends ask them in advance what kind of things they want to eat, what toppings they want on their pizza and what kind of beer they like.

#12. When carrying things for many hours have a 5 minute to 10 minute break every hour. It will give people a chance to catch their breath and get a drink, eat an energy bar, etc. People will be able to carry things better and be more sure-footed if they aren't exhausted or hungry.

BONUS TIP: Buy a box of energy bars for everyone.

Saturday, May 12, 2012

Vancouver's Real Estate Woes

Toronto isn't the only city in Canada which is facing a market correction.

Vancouver has also seen real estate prices soaring in the stratosphere.

However I don't think Vancouver and Toronto will see market corrections at the same time. Their economies are separated by 4492 km and very different market modifiers.

Those modifiers are:

The amount of local demand for real estate. How many people are looking to buy?

The amount of real estate investors in Vancouver. How many are looking to flip for a profit?

The amount of available supply of houses and condos (and rental supply).

The amount of upcoming supply of houses and condos (and increasing rental supply).

The strength of the local economy (the employment rate + the median salary of the middle class).

Local consumer confidence.

Local household debt.

Ratio of average home sale prices to the middle class median income. (No point using lower class incomes because many of them can't afford to buy homes, diddo for wealthy people who have more stable incomes.)

Local demographics (ie. What age groups are buying condos? Elderly? Young professionals? Families?)

And lastly the ratio of housing starts vs condo starts.

ie. In Toronto housing starts has dropped, but condo starts are through the roof. Mostly due to the rising price of land and the air-space is comparatively cheap.

In Vancouver? Housing starts were steady in April 2012 (but up in the rest of British Columbia) and have been growing steadier since the huge market decline in 2009. But its the volume of condo starts in Vancouver which are worrying.

In Toronto (not the GTA) the average price of a house reached $568,436 in April 2012. The average price for a detached single-family home hit $831,214 (doubled in price since 2002), according to TREB.

In contrast the average single detached home in Vancouver runs over $1 million, but the market for homes is softening while the condo market is heating up.

So evidently the high prices of houses is fueling the demand for condos, which is causing prices to skyrocket.

Price growth in the GTA are up 10% compared to one year ago (and household debt is likewise up, but salaries are stable). Its a bidding war in Toronto due to lack of supply for homes and the high price of land even in Toronto's satellite cities.

Restrictive Greenbelt policies, strong immigration and low interest rates have kept demand in the GTA high.

Vancouver likewise has benefitted from strong immigration and low interest rates, and judging by the housing growth centres in Vancouver most of the demand is near the shoreline.

According to BMO Deputy chief economist Doug Porter the softening in Vancouver's housing market could see foreign investors, who fueled Vancouver prices, start looking to Toronto as a new place to invest.

The worry however is that the investors ditching of Vancouver (whenever it happens) would cause Vancouver's real estate market to go into a tailspin, and then if Toronto's market overheats a year later the investors will ditch Toronto amidst a similar collapse in prices.

So... here is my prediction. Vancouver's condo and housing bubble may burst first, Toronto's market will go into overdrive (creating an even bigger bubble) and then when Toronto's real estate bubble will burst too when it gets too hot for buyers.

In which case there are two possibilites in terms of a price correction for both Toronto and Vancouver:

Option 1: A minor price correction, going down slightly and then buyers jumping on the opportunity. (Which means a larger correction will be delayed, possibly for years.)

Option 2: A major price correction, with buyers waiting until prices bottom out before taking advantage of the super low prices.

Me? I would prefer a larger correction. The prices on both Vancouver and Toronto are outrageous.

Thursday, May 10, 2012

Is Household Debt the real estate market's Achilles Heel?

I have just returned from the studios in the CBC building in downtown Toronto where I was on CBC Radio discussing "My Quest for a Condo" and also Toronto's real estate bubble.

During the interview I asserted that household debt is the largest factor in Toronto's (and Canada's) real estate market.

So am I right? Is Household Debt the real estate market's Achilles Heel?

Yes, but its not the only factor.

The problem with having a radio interview is you can really only provide snippets of conversation within your allotted 6 minutes. There are many factors that go into the hows and whys the Toronto real estate market is going to have a US-style collapse within the next 3 years.

Exactly when I cannot predict, but I can pretty much guarantee it is going to happen when you consider ALL the factors.

#1. 60% of recent buys in Toronto's new condo market are from investors looking to flip the property for a profit. (Source: real estate research firm Urbanation) When Toronto's real estate market hits a serious bump they will sell the properties in a panic.

#2. Interest rates in Canada are currently super low, but if they go up too quickly it will hurt home and condo sales. If they don't go up or barely go up it will encourage an expansion of the current bubble by making credit too easily available.

#3. Foreign investors are taking advantage of Canada's banking and mortgage system wherein the banks put up the cash, the government takes the financial responsibility via the CMHC (Canada's version of Fannie Mae and Freddie Mac) as mortgage insurer and the foreign investors can cut and run if anything goes wrong. Real estate speculators are like sheep. They flee any market they can't make a profit in.

#4. Household debt in Canada is at an all time high. $1.61 TRILLION Canadian dollars.

#5. In 2012 banks started to refuse to give many Canadians more credit because they've recognized the threat of household debt (and financial losses from future bankruptcies). Too many bankruptcies will hurt bank profits so instead they're cutting back on credit availability.

#6. Less credit in Canada's current economic climate means a lowered consumer confidence level. People go out and spend less, tighten their belts and lack of spending = downward spiral into recession.

#7. Rising cost of living in Canada. Prices of food, gasoline and basic goods are all going up (partially due to high oil prices). Since food, gasoline and toilet paper are considered necessities it cuts into the household budget for other things (such as saving up for a house or condo).

#8. Toronto developers are currently building almost 3 times as many skyscrapers as New York City is currently building. Its a lot of skyscrapers. History has shown that developers start building skyscrapers en masse right before a major financial meltdown because land becomes too expensive but credit is too easily available so the only solution is to build vertically.

#9. Many investors rent out their condos and wait for a good time to sell. The rent income pays for the mortgage and its low risk. However if condo prices stagnate or prices drop it becomes high risk and they will be looking to sell in a hurry to prevent taking losses.

I could go on and on, but essentially the economy and housing market is a proverbial House of Cards and household debt/credit is the linchpin which holds it all together.

All it will take is a nudge to cause the collapse.

And here is the nudge that will do it:

Toronto currently has 148 high-rises and skyscrapers being built including 105 new condo buildings (and more scheduled for 2013 - 2015). Right now we are building 27,504 (a 14% increase), but there isn't the demand for it. When that extra 27,504 condos hits the market during the next 3 years it will cause condo prices to drop dramatically... which combined with household debt and people reneging on mortgages (or banks refusing to give them refinancing) will push a market correction.

So yes, household debt is the Achilles heel... but its too much condo supply during the next 3 years that is the ticking time bomb waiting to go off.

Thursday, April 19, 2012

American real estate websites are interesting

For fun I sometimes look at real estate websites in the USA. I especially like real estate websites from Hawaii, just because its exotic.

Lets take midsouthhomebuyers.com for example, a website which specializes in Memphis real estate investing which basically means they take your money and invest it in rental properties, rent the property out and then you receive a portion of the rent.

Its an interesting concept... but what is more interesting is the question of how much these properties are actually worth. Remember that Memphis was hard hit during the US recession of 2007-2009.

From 2006 to early 2009 the median prices of homes in Memphis dropped from $105,000 and dropped down below $75,000. Right now the median price is hovering around $85,000.

Compared to prices here in Toronto, real estate in Memphis is dirt cheap.

Now I admit that is not as cheap as some other locations (ie. Detroit), but it is still a bargain.

What midsouthhomebuyers.com does therefore is hunt around for bargains, then flip them as rental properties and eventually (when the real estate market has recovered) sell it for a profit.

Lets say you buy a property for $100,000 and rent it out for $1,000 per month. 2 years later, depending on the demand, you might be able to sell the same property for $110,000... and better yet you've pocketed $24,000 (minus property taxes, income taxes, maintenance costs and lawyer fees) from the rent.

If you look at the ROI (Return on Investment) for many of the properties on midsouthhomebuyers.com it varies between 32% and 48%. It really makes you realize that renters in the USA are getting bushwhacked by high prices and that investors are cleaning up and laughing all the way to the bank.

I do think you could do this yourself, assuming you had enough spare cash. My uncle David and an investment partner did this years ago back during the 1970s and 1980s. They bought several properties near Niagara Falls, waited for them to shoot up in value and then sold them all. Then (for fun) the two of them had the bank give all the money to them in cash, bought some champagne and rolled around in the cash. My uncle even has photos of the event of him and his buddy rolling around drunk in all the cash.

So you can make a lot of money investing in real estate. You can go through a company or broker that specializes in it or you can do it by yourself or with an investment partner.

And in places like the USA where the economy collapsed a few years ago its easier to find deals where if you invest wisely (and spread the money over multiple properties, thus alleviating the risk) you can make a bundle.

During the height of the recession in Detroit there was properties being sold for $1. Just one dollar. They had been seized by the federal government for failure to pay back taxes. If a person wanted to buy those properties they could fish around, check which properties could be snapped up for $1 and whatever the back taxes were and they could get a chunk of land which 10 years from now might be worth $50,000 to $100,000 or more when the economy has recovered and Detroit becomes a desirable place to live in again. Too late now. All the really nice properties have been snapped up.

Cities like Memphis in comparison are less risky. The economy there is better. The prices are higher and the ROI is less, but at least there is comparatively little risk.

Food for thought.

Monday, March 05, 2012

Toronto Condo Bubble might burst

CANADA - What happens when you have too much supply, ridiculously high prices and not enough people buying?

The answer is obvious. The bubble bursts.

Toronto keeps building more and more condos, so many in fact that it is above and beyond the demand to actually buy condos.

Lets take for example Ten York...

Ten York is a 75-story glass condo building which 4 years from now will be the 3rd tallest condo in all of Canada. Currently the site is a parking lot and a police impound, but the chunk of land beside the freeway will see a lot of construction in the next couple of years and it is not alone.

Toronto is building more skyscrapers and high-rises than any North American city... in fact Toronto is building almost 3 times as many as New York City is currently building. And we all know Canada's largest city is small potatoes compared to New York City.

So why are we building 3 times as many condos and skyscrapers? Do we need the extra homes close to downtown Toronto and the extra office space?

What is also silly is that Toronto's condo market is pretty soft. There isn't a huge demand, but investors in Toronto's construction industry seem to think this will change.

(But what those investors don't realize is the correlation between building skyscrapers and stock market crashes... see my older article Skyscrapers = Recession.)

Meanwhile average home prices in Toronto is just under $500,000, prices are at record highs and household borrowing is also at a record high. Torontonians are piling on so much debt that if anything happens there will be a huge collapse. Canadian lenders are worried too: The Toronto-Dominion Bank last week raised mortgage rates in an effort to cool off the housing market.

TD Bank isn't alone in its thinking that Toronto is heading towards a condo market burst.

“Condo construction has always been rather prone to boom and bust cycles, and this one seems particularly strong,” says Sheryl King, an economist with Bank of America Merrill Lynch in Toronto. “Builders seem to overestimate how much demand is going to be out there, and that’s when you tend to see some abrupt pull-back.”

According to King, Canada’s housing market is already about 10% overvalued, with inflated prices primarily in Vancouver, Montreal and Toronto. “We would call it a bubble,” she said.

Rising home prices have led to a 53% increase in residential mortgage credit in the past five years, or an average rate increase of 8.9% per year. The volume of outstanding mortgages rose to $1.08 trillion CDN as of August 2011, according to the Canadian Association of Accredited Mortgage Professionals. Defaults currently remain low, at 0.42%, according to government-run housing agency Canada Mortgage & Housing Corp., but if something happens that causes sales to drop off, prices to fall... then defaults could skyrocket.

Too much supply 4 years from now could do just that. Toronto's housing market prices could collapse up to 50% and end up with prices comparable to those in the USA.

Canada’s financial authorities have become increasingly worried and vocal about the possibility of a housing market collapse. The Bank of Montreal and Royal Bank of Canada, Canada’s banking regulator, and Bank of Canada Governor Mark Carney have all expressed worries about the condo markets in 2012 as cranes and construction crews swamp Toronto. They're all fearing a construction led bust which would lead to a recession in Ontario and then effect the rest of Canada.

Toronto currently has 148 high-rises and skyscrapers being built, compared with 59 tall buildings being built in New York City, and 22 going up in Chicago.

Most of the buildings in Toronto is 105 new condo buildings, but there are many more scheduled for the next 4 years. 14 buildings will be finished in 2012, including two hotel-condos: Trump International Hotel & Tower Toronto, which will be Canada’s tallest residential building. Tower Toronto opened January 31st.

What is also interesting is the number of units being constructed. These condos are bigger and more impressive than ever before. Condo builders seem to be competing in an effort to get taller and more luxury units into one building.

“The number of units under construction is quite high, start levels have trended up, and the number of units coming to completion is growing,” says Shaun Hildebrand, a senior market analyst for the Greater Toronto Area with Canada Mortgage & Housing Corp. “Supply at all ends of the development process is growing quite quickly.”

Too much supply.

Toronto currently has 199,000 condo units, but another 27,504 are under construction right now. That will boost supply by roughly 14%. In theory that much extra supply dumped on the market should cause prices to drop roughly 8 to 12%.

If the condo market sees a price drop it will also effect home prices as the supply of cheap condos will make new home buyers think twice about whether to buy a house in the suburbs or a condo downtown.

Add in Toronto's slow population growth and you also realize 14% extra condos seems abnormally high.

“If builders stopped building today, there’s five years worth of supply that is about to be delivered, relative to what normal population growth is,” says Sheryl King of Bank of America.

Then there is the problem of over-investment.

Investors are flooding Toronto’s condo market because of cheap borrowing costs and taking a risk that real estate prices will continue to go up. Its the same risk that the USA was taking in the 2000s before the market collapsed.

“They’re being bought because the interest rate is very low,” says John Andrew, a real estate professor at Queen’s University. “They’re financed to the hilt, so they’re very sensitive to the refinance risk when the loans come up.”

Meanwhile all of Canada's big banks are selling mortgage bonds to investors overseas, worried that when the market does collapse the banks would take a huge financial loss. Bank of Montreal and Bank of Nova Scotia sold $4.5 billion of their mortgage securities last month, after a record $25 billion of sales in 2011. They're getting rid of those debts because they sense the danger on the horizon.

Part of the problem is that when the recession in the USA hurt investment many foreign investors turned to Canada with their money because Canada seemed like a more stable option. They flooded the Canadian market with extra credit and now Canadians are mortgaged and indebted over their heads. Those foreign investors are going to be hurting when the real estate bubble in Canada bursts.

“The stability of Canada has moved it to the forefront of investor preference, in some cases ahead of the U.S.,” states a draft analysis of Toronto’s condo market, but that overconfidence in Canada's stability will be our undoing.

Right now investors represent roughly 25% of Toronto’s condo market and while high-rise home sales are at record heights (62% of Toronto's real estate market is condo sales) the demand still isn't enough to compete with the 14% increase we will see in the next 4 years.

And mortgage lenders aren't expecting demand to keep going up. They're expecting condo demand to hold steady as long as the economy remains stable.

Toronto accounts for 11% of Canada’s economic output. The city is home to Canada’s five-biggest banks, two of the three largest Canadian insurers as well as some of the country’s largest pension funds, asset managers and financial-services firms. Toronto is epicentre of Canada's finances.

So the theory goes that between immigrants, investors and young urbanites condo demand will continue to grow. And yet if that were true, why are the Canadian banks selling those debts overseas unless there was a real danger of a collapse?

Do the banks know something we don't?

Friday, February 17, 2012

Toronto real estate bubble grows 3.8%

CANADA - House sales are down across Canada, including Toronto where the average house prices continue to go up despite lagging sales. The average price of a home in Toronto is now just under $500,000 as of January 2012.

Sales are down in over half of Canada. One of the biggest declines are in Toronto and the GTA where sales are down 3% (including seasonal adjustments), according to January housing statistics released Wednesday by the Canadian Real Estate Board (CREA.)

New listings are also down a seasonally adjusted 4.3% across the GTA, resulting in very low inventory of new resale properties on the market.

The low inventory (shortage of supply) is helping to drive up the average house price in the GTA by 3.8%, increasing Toronto's real estate bubble. The average sale price in the GTA from December 2011 to January 2012 to $486,654, according to CREA.

It is estimated the average price in the GTA will reach $500,000 by July or August 2012. The average price only needs to go up an extra 2.8% for it to reach $500,000.

The average GTA home was worth about 8.5% more in January than over the same period a year ago, the statistics show.

Across Canada the average price of a Canadian home hit $348,178 in January, up 1.2% from a year earlier.
Moffat Inspections provides thorough and reliable home inspections throughout Ajax, Pickering, and the Durham Region. The company focuses on uncovering potential issues before they become expensive problems, offering clear and practical reports that homeowners and buyers can actually understand. From foundations and roofs to plumbing, heating, and electrical systems, Moffat Inspections delivers detailed, honest assessments — no gimmicks, no guesswork. For professional property inspections done right, visit moffatinspections.ca.

Recently Popular Posts